FMCSA won’t make you insure freight. The law makes you liable anyway.
Kamyar Shah, Revenue Operations, World Consulting Group.
FMCSA won’t make you insure freight. The law makes you liable anyway.
Kamyar Shah, Revenue Operations, World Consulting Group.
Your AI doesn’t forget. Every session, your context does.
Kamyar Shah, Fractional Executive, World Consulting Group.
Every tech prices the same repair differently. Your margin pays.
Kamyar Shah, Revenue Operations, World Consulting Group.
Your last efficiency push faded. The waste quietly came back.
Kamyar Shah, World Consulting Group.
Your agency hits every KPI while your pipeline stays flat.
Kamyar Shah, Fractional Executive, World Consulting Group.
You’re the best person to grow the practice — with no time to.
Kamyar Shah, Revenue Operations, World Consulting Group.
Your remote stars do great work. They never get promoted.
Kamyar Shah, World Consulting Group.
Great product, wrong channel, and it sells like it’s invisible.
Kamyar Shah, Fractional Executive, World Consulting Group.
You need a COO’s discipline. Not a COO’s salary.
A full-time COO is six figures plus benefits and equity. At $2.5M you don’t need the headcount — you need the operating discipline one brings: KPIs, cadence, and someone who makes the trains run.
Kamyar Shah, Fractional COO, World Consulting Group.
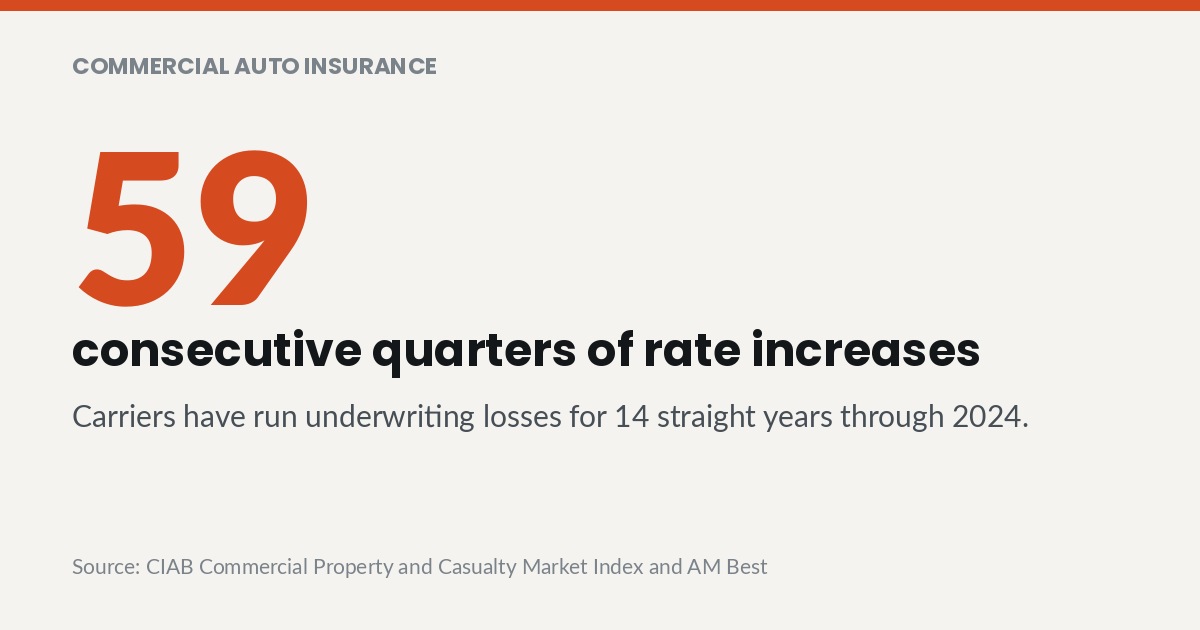
A DOT compliance consultant earns the fee in the insurance market, not the audit file. Commercial auto premiums rose 5.8 percent in Q1 2026, the highest increase of any line in the CIAB Commercial Property and Casualty Market Index. That is 59 consecutive quarters of increases since Q3 2011. Safety data is what breaks the pattern for a single fleet.
A market cycle implies a turn that eventually arrives. Commercial auto has not produced one since the third quarter of 2011, according to the CIAB Commercial Property and Casualty Market Index. The Q1 2026 reading of 5.8 percent was the highest increase of any line in that survey.
The reason is visible on the carrier side of the ledger. AM Best records net underwriting losses in commercial auto for 14 straight years through 2024, and 15 counting the 2025 loss. Insurers raising rates for 59 consecutive quarters while still losing money on the line are not extracting rent. They are chasing a loss cost that keeps moving away from them.
That distinction matters for how a fleet plans. An operator budgeting for the market to soften is budgeting against 15 years of contrary evidence. The rational plan assumes continued pressure and works on the one variable the operator actually controls.
The US Chamber Institute for Legal Reform studied verdicts at the top of the distribution. Its sample covered 1,288 personal injury and wrongful death verdicts of $10 million or more between January 1 2013 and December 31 2022. Auto accident verdicts within that sample carried a median of $21.0 million and a mean of $46.4 million.
The distance between median and mean describes a tail rather than an average. Across all personal injury and wrongful death categories in the same study the median was $21.1 million and the mean $88.9 million. A small number of outcomes drags the average far above the midpoint.
That shape is what reprices an excess liability tower. Primary limits absorb the routine file without much drama. The verdicts that move an insurer's reserves land in layers most mid-market fleets did not think they needed.
Severity exposure also changes what a claim file has to look like from day one. Plaintiff counsel builds a severity case out of documents the fleet created before the crash. Maintenance records, hours of service logs and hiring files become exhibits rather than paperwork.
An operator cannot change the litigation environment. Jury behavior, attorney advertising volume and third-party litigation funding sit outside any fleet's reach. The same holds for medical cost inflation and for the reinsurance pricing that flows into excess layers.
What the operator does control is the individual file the underwriter prices against. Rate is built from an industry loss cost adjusted for the specific account, and the adjustment is where the negotiating room lives. Fleets treating their safety record as an input to that adjustment recover part of the industry pressure.
The lever works because the underwriter has limited information about any given account. Loss runs, roadside inspection history and CSA percentiles are close to everything an insurer knows about a mid-market fleet before binding. Each of those is generated by the operator's own daily practice rather than by the market.
That also explains why the effect takes time to arrive. Loss runs cover multiple years and roadside history accumulates over a rolling window. A program started this quarter shows up in pricing two renewals out, which is why fleets waiting for a hard renewal to act are always late.
The exposure side of the equation is moving in the operator's favor. National Safety Council analysis of NHTSA FARS data for 2024 counted 5,218 large trucks in fatal crashes, down 3 percent from 2023. The rate was 1.58 per 100 million large-truck vehicle miles traveled.
The trend line in that series is not noise. The same NSC series ran 1.68 in 2019, 1.62 in 2020, 1.75 in 2021, 1.77 in 2022, 1.63 in 2023 and 1.58 in 2024. The rate peaked and came down, and it now sits below where it stood before the pandemic.
Frequency falling while premium rises is the clearest available proof that severity is doing the work. Underwriting math multiplies frequency by severity, and only one of those terms is cooperating. A fleet that improves its crash frequency and expects a proportional rate credit will be disappointed.
The disconnect also shapes what a rate presentation should emphasize. An operator leading with improved crash frequency is arguing on the term that is already falling market-wide. The stronger argument covers severity control, meaning documented training, post-accident procedure and the evidence that limits how a claim develops.
One exposure inside the 2024 data moved the wrong way. NHTSA data for 2024 shows alcohol-impaired large-truck drivers in fatal crashes rose to 224 from 178, an increase of 26 percent. Large trucks were the only vehicle type that increased on that measure.
That single statistic is a case theory waiting to be written. A plaintiff attorney will use it to argue that industry screening and supervision practices are failing. Fleets with documented testing programs and supervisor training answer that argument with records rather than testimony.
Submissions are underwritten on loss runs, safety rating and roadside inspection history. Those three items describe a fleet more honestly than any narrative in the application. Out-of-service rates in particular give an underwriter a defensible benchmark.
Loss run presentation is where most mid-market submissions give away money. A raw export shows claim counts and reserves without explaining what changed after each one. Fleets that annotate their loss runs with the corrective action taken give the underwriter a reason to price the future rather than the past.
The FMCSA Pocket Guide, drawing on MCMIS data for calendar year 2023, reports a driver out-of-service rate of 6.4 percent and a vehicle out-of-service rate of 22.6 percent. CVSA reported an 18.1 percent vehicle out-of-service rate and a 5.9 percent driver rate across 56,178 inspections during its 2025 International Roadcheck. A fleet sitting above those benchmarks is telling the underwriter something specific about its maintenance program.
CVSA recorded 5,561 brake violations in 2025, accounting for 41.1 percent of vehicle out-of-service violations. Brake defects are a preventive maintenance interval problem rather than a capital problem. A fleet that shortens its inspection cycle and documents the result changes that number within a quarter.
Hours of service was the top driver out-of-service violation in the 2025 CVSA data at 1,076 findings, or 32.4 percent. Electronic logging made those violations visible without making them disappear. Fleets that audit logs weekly and coach on the exceptions convert an underwriting liability into evidence of supervision.
CSA percentiles are visible to underwriters, brokers, shippers and plaintiff counsel at the same time. A fleet managing them only at renewal is managing them for the wrong audience. The score reflects roadside behavior over a rolling window, which means correction takes months and neglect compounds quietly.
Most fleets treat DOT compliance as a threshold to clear. Treated that way it produces a passing score and no premium benefit. Treated as an underwriting submission it becomes the most cost-effective insurance spend available to a mid-market operator.
The mechanics of building that submission are unglamorous and cheap. A driver scorecard combining telematics events, roadside results and preventable accidents gives an underwriter a management story with numbers behind it. Dashcam footage resolves liability questions early, which matters most in exactly the severity environment the verdict data describes.
Submission quality is a separate discipline from safety performance. Two fleets with identical loss runs receive different quotes when one explains its trend and the other sends a form. Operators who want that framing built properly often bring in outside operating help. A management consulting engagement covering risk and operations tends to pay for itself within a single renewal.
Timing matters as much as the content of the file. Submissions assembled in the last week before expiration reach underwriters with no room to ask questions. A fleet that puts its package together well ahead of renewal gets a market that competes rather than a market that declines.
Structural options open up once the data is clean. Higher retentions, captive participation and group programs all require a loss history an underwriter will accept at face value. Fleets that cannot document a safety program have no access to those structures and pay guaranteed cost rates instead.
The commercial auto market has spent 59 quarters telling operators the same thing. Price follows severity, severity follows litigation, and litigation follows the documents a fleet created before anything went wrong. Operators who treat compliance records as future exhibits rather than regulatory chores are the ones whose renewals stop surprising them. That is an operating decision rather than a rate strategy.
Does hiring a DOT compliance consultant actually lower insurance premiums?
Premium outcomes follow the underlying data rather than the engagement itself. A consultant who reduces out-of-service findings, clears hours of service exceptions and documents a preventive maintenance program changes what the underwriter sees at renewal. Fleets with clean roadside histories and explained loss runs receive better terms than fleets carrying the same losses with no narrative. The effect arrives over renewal cycles rather than immediately.
How long should my fleet expect commercial auto rates to keep rising?
The CIAB Commercial Property and Casualty Market Index has recorded 59 consecutive quarters of commercial auto increases since Q3 2011. AM Best records net underwriting losses on the line for 14 straight years through 2024. Rates rising while insurers still lose money indicates the pricing has not yet caught the loss cost. Planning around a soft market means planning against the entire available record.
What out-of-service rate should my fleet be targeting?
National benchmarks give the reference point for any target. The FMCSA Pocket Guide, using MCMIS data for calendar year 2023, reports a driver out-of-service rate of 6.4 percent and a vehicle rate of 22.6 percent. A fleet materially above those figures will be underwritten as a maintenance risk regardless of its loss history. The goal is less a specific number than a documented downward trend.
Are dashcams worth the cost and the driver resistance?
In a severity-driven market the value sits in liability resolution rather than in coaching. Footage that establishes fault early prevents a routine claim from developing into the kind of file the verdict data describes. The US Chamber Institute for Legal Reform found auto accident verdicts in its large-verdict sample carried a median of $21.0 million. Against that tail, camera hardware cost and internal friction are minor considerations.
Should a mid-market fleet consider a captive or a higher retention?
Those structures reward fleets whose loss data is both clean and credible. Higher retention transfers volatility back to the operator, which works only when frequency is controlled and severity is insured above it. Captive participation requires a safety program an underwriter will underwrite rather than merely tolerate. Fleets without documented processes should fix the record before changing the structure.
What should a fleet fix first if resources are limited?
Brake maintenance and hours of service auditing address the two largest categories in the CVSA data. CVSA recorded brake violations at 41.1 percent of vehicle out-of-service findings in 2025 and hours of service at 32.4 percent of driver findings. Both respond to process discipline rather than capital investment. A fleet that fixes those two areas moves its inspection profile faster than through any other single action.
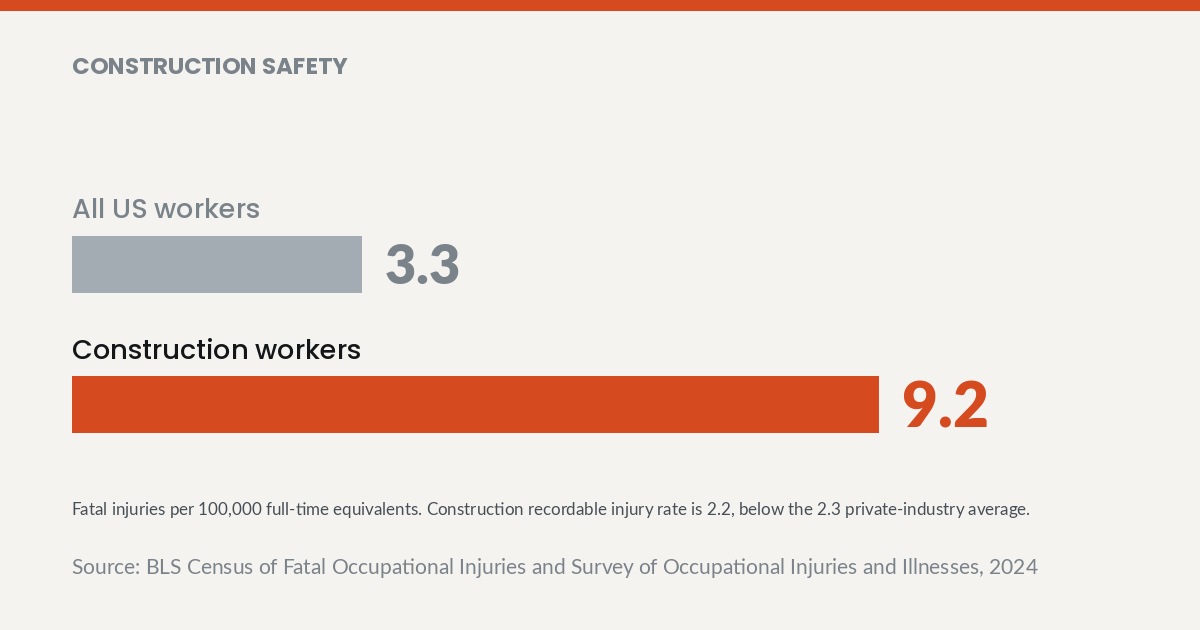
Construction workforce management fails when safety programs are graded on injury frequency. BLS data for 2024 puts the construction total recordable case rate at 2.2 per 100 full-time equivalents, below all private industry at 2.3. That same year, the construction fatal injury rate was 9.2 per 100,000 against 3.3 for all US workers.
The BLS Survey of Occupational Injuries and Illnesses for 2024 shows construction recording fewer injuries per worker than private industry overall. The BLS Census of Fatal Occupational Injuries for the same year shows construction killing workers at nearly triple the all-industry rate. Both statements come from the same agency and the same reporting period.
Most safety programs are designed against the first number. Recordable rate and DART drive scorecards, bonus formulas, and prequalification thresholds across the industry. Those measures track how often something goes wrong rather than how badly.
Specialty trade contractors sit at 2.3 total recordable cases and 1.4 DART per 100 full-time equivalents, according to BLS. Those figures describe a workforce that gets hurt about as often as an average private-sector workforce. The fatality data describes a workforce operating in a fundamentally different hazard class.
BLS counted 1,034 construction fatal work injuries in 2024. Specialty trade contractors accounted for 606 of them. Any program that treats construction as one undifferentiated risk pool is averaging across very different exposures.
Falls, slips and trips caused 389 deaths in construction during 2024, or 37.6 percent of the total, according to BLS Census of Fatal Occupational Injuries Table A-9. No other event category in the construction data comes close to that share. A fall exposure that produces no recordable injury for months still carries the same lethal potential every day it exists.
Frequency-based programs handle this badly by design rather than by accident. A crew working at height without incident generates a clean recordable rate and an unchanged risk profile. The scorecard rewards the absence of consequences rather than the absence of exposure.
OSHA enforcement reflects the same pattern from the other direction. The fall protection standard 1926.501 is the most cited standard in OSHA construction data, with 6,769 citations and $44,969,484 in penalties in FY2025 according to OSHA IMIS records. Enforcement follows the fatality distribution more closely than most internal safety programs do.
That alignment is worth sitting with for a moment. The regulator and the mortality data agree on where the danger concentrates, and the industry scorecard does not. A contractor optimizing for recordable rate is optimizing against a measure that neither OSHA nor the coroner uses.
BLS recorded 90 construction worker deaths from drug and alcohol overdose in 2024, or 8.7 percent of the total. Electrocutions killed 52 construction workers that year, or 5.0 percent of the total. One of those categories has a dedicated OSHA standard, a toolbox talk library, and a decade of training material behind it.
The other sits almost entirely outside the safety function. Overdose deaths get handled by human resources, by employee assistance programs, or by nobody at all. The fatality data says that allocation of attention no longer matches the actual risk.
Construction workforce management has to absorb this shift in the risk profile. Injury history, opioid prescribing after those injuries, and irregular schedules all interact in ways that a jobsite audit cannot detect. A safety committee that never discusses substance risk is ignoring a larger killer than electricity.
The reporting structure makes this harder than it needs to be. Safety directors report incident data upward and rarely see the health plan or leave data that would flag the same population. Contractors that connect those views find the risk before it becomes a fatality line in a federal table.
OSHA IMIS data for FY2025 shows specialty trade contractors carrying 23,197 citations and $92,678,478 in penalties. That represents 87.3 percent of all construction citations. Enforcement pressure concentrates in the same segment that accounts for most construction deaths.
The OSHA serious violation maximum penalty stands at $16,550, unchanged from 2025 because no 2026 inflation adjustment was issued, per an OSHA memo dated May 21 2026. A flat penalty ceiling does not mean flat exposure. Citation counts multiply, and the segment-level totals show what that multiplication produces.
Prequalification systems in construction mostly ask for recordable rate, DART, and experience modification. A contractor can present clean numbers on all three while running the exact exposures that produce the fatality statistics. Owners and general contractors accepting those numbers as sufficient are buying comfort rather than information.
The concentration figure deserves particular attention from general contractors. Specialty trades absorb the overwhelming share of both citations and construction deaths, which means selection decisions carry more weight than internal policy. A general contractor with excellent internal programs and weak subcontractor screening still owns the resulting exposure.
NCCI reports in its 2026 State of the Line that construction carries the lowest workers compensation claim frequency of ten industry groups and the steepest frequency decline. The same report places construction at the highest medical claim severity, rising roughly 13 percent year over year. Frequency down, severity up, in one industry, in one report.
That divergence explains why workers compensation premium behavior confuses contractors who have improved their injury counts. Experience modification responds to claim history, and severe claims dominate the calculation. A contractor can reduce incidents and still watch costs climb.
Insurers are reading the same signal the fatality data sends. Construction injuries are becoming less common and more expensive when they happen. Any program that optimizes only for the first half of that sentence will keep producing unpleasant renewal conversations.
Brokers rarely frame it this plainly for their construction clients. The frequency improvement gets celebrated in the renewal meeting because it reflects genuine effort. The severity trend then arrives as a surprise in the premium, and the contractor concludes that safety investment does not pay.
The practical change is not more safety activity. It is a different unit of measurement inside the same activity. Programs that track exposure to fatal-class hazards produce different behavior than programs that track incident counts.
A leading indicator worth tracking answers how many crew-hours occurred at height, near energized equipment, in excavations, or under suspended loads. Those counts move well before anyone gets hurt. Recordable rate and DART are lagging indicators that report the past and predict very little.
Collecting exposure hours requires nothing more than a field added to the daily report. Foremen already record crew size, hours, and work performed for payroll purposes. Tagging that entry with hazard class turns existing paperwork into a forward-looking risk measure.
Toolbox talks improve when they are scheduled against measured exposure rather than a rotating topic calendar. A crew spending the week on leading edge work should hear about fall protection that week. Generic rotation guarantees that the right message arrives at the wrong time.
Jobsite audits should be weighted the same way. An inspection that scores housekeeping and personal protective equipment equally with fall protection anchorage is producing a misleading score. Weighting audit findings by fatal potential changes what supervisors chase.
With 599,074 specialty trade contractor establishments recorded by BLS QCEW in Q4 2025, subcontractor selection is the most consequential decision in construction workforce management. Most prequalification forms request the metrics that correlate weakly with fatality risk. Adding questions about fall protection program specifics, competent person designation, and pre-task planning practice yields far more signal.
Safety culture shows up in answers about near-miss reporting rather than in incident totals. A subcontractor reporting many near misses and few injuries is managing exposure actively. A subcontractor reporting nothing at all is usually not measuring anything.
Firms rebuilding prequalification standards and field reporting systems at the same time run into an operating-model problem rather than a safety problem. That work sits closer to operational management consulting than to compliance, because it changes how projects get staffed and supervised.
Overdose fatalities will not decline through testing policy alone. Workers who fear termination do not disclose, and the exposure stays invisible until it becomes a fatality statistic. Contractors that build confidential support pathways see disclosure rates that testing alone never produces.
The operational cost of that approach is modest compared with the exposure. The alternative is a fatality category that BLS now ranks above electrocution, managed by nobody in particular. Contractors that name an owner for it are ahead of nearly everyone in the industry.
Construction has spent decades getting genuinely better at preventing injuries, and the recordable data proves it. The fatality data proves that this improvement did not transfer to the outcomes that end careers and lives. Those two facts have coexisted for years without forcing a change in how programs are measured. A contractor who takes both numbers seriously stops asking how often people get hurt and starts asking how close the work comes to killing someone. Those questions have different answers and lead to different jobsites.
Why is the construction recordable rate below average if the industry is so dangerous?
Recordable rate measures how often injuries occur, not how severe they are. BLS data for 2024 shows construction at 2.2 total recordable cases per 100 full-time equivalents against 2.3 for all private industry. The fatal injury rate tells the opposite story, at 9.2 per 100,000 against 3.3 for all US workers. The industry has improved at preventing common injuries without proportionally reducing lethal exposures.
Should my firm still track DART and recordable rate?
Both metrics remain necessary because owners, insurers, and prequalification systems require them. They should not serve as the primary measure of program effectiveness. Firms that add exposure-based leading indicators alongside the required lagging metrics get a far more accurate picture of fatal risk. The two sets of numbers answer different questions and both belong on the report.
What is the single highest-value safety investment in construction?
Fall protection consistently returns the most, based on both fatality distribution and enforcement data. BLS attributes 389 deaths, or 37.6 percent of construction fatalities in 2024, to falls, slips and trips. OSHA cites standard 1926.501 more than any other, with 6,769 citations in FY2025. Investment in anchorage planning, competent person capability, and pre-task review addresses the largest identified killer directly.
How should overdose risk be handled on a jobsite?
BLS recorded 90 construction overdose deaths in 2024, which exceeded the 52 electrocution deaths that year. Effective responses combine confidential support access, supervisor training on impairment recognition, and injury management practices that reduce prolonged opioid exposure. Punitive-only approaches drive the behavior underground and eliminate the chance to intervene. The category needs an owner inside the organization rather than a policy paragraph.
Why did workers compensation costs rise even though injuries fell?
NCCI reports in its 2026 State of the Line that construction has the lowest claim frequency and steepest frequency decline of ten industry groups. The same report places construction at the highest medical claim severity, rising roughly 13 percent year over year. Fewer claims that cost more can produce a higher total than more claims that cost less. Experience modification reflects claim cost, so severity dominates the calculation.
What should subcontractor prequalification actually ask for?
Standard forms collect recordable rate, DART, and experience modification, all of which correlate weakly with fatality exposure. Stronger prequalification adds questions about competent person designation, fall protection program specifics, pre-task planning practice, and near-miss reporting volume. A subcontractor reporting many near misses and few injuries is usually managing exposure well. With 599,074 specialty trade contractor establishments in the BLS QCEW count for Q4 2025, selection quality drives program outcomes more than any internal policy.
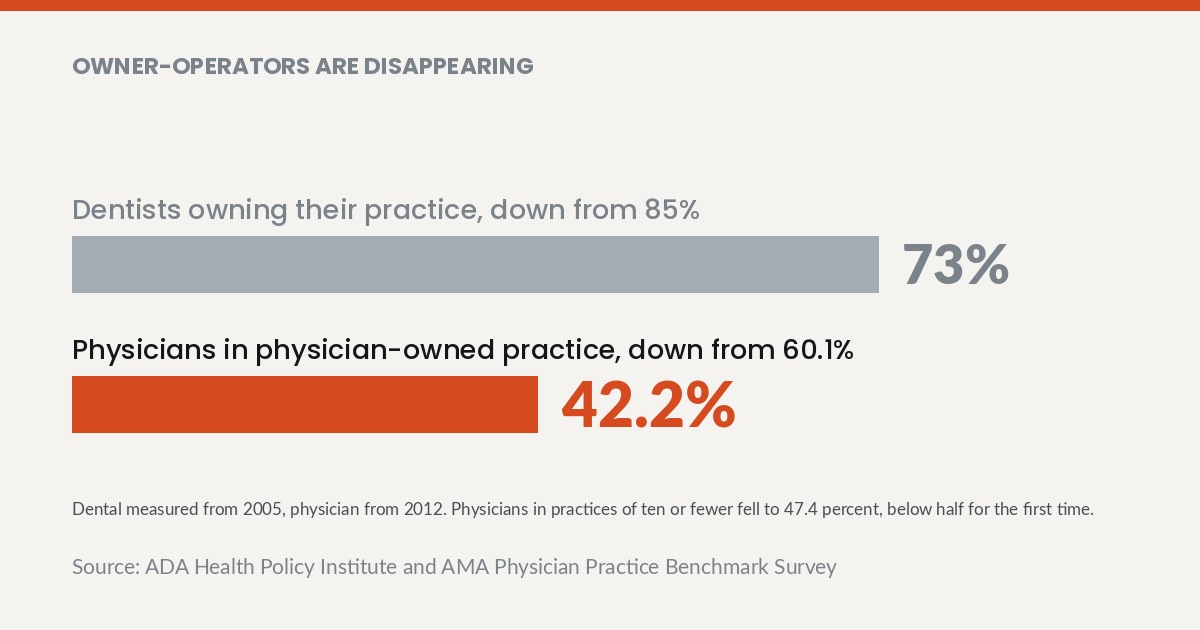
A fractional COO supplies senior operating leadership part-time to companies too small to employ one full-time. Demand for that role is concentrated where owner-operators are exiting. Physicians in wholly physician-owned practices fell to 42.2 percent from 60.1 percent in 2012, according to the American Medical Association. Acquirers bring a management layer. Independents have to build one.
Consolidation stories are normally told one profession at a time. Dental gets a trade press narrative about dental service organizations. Medicine gets a policy debate about hospital employment. Law gets a merger tally. Each account treats its own industry as the special case.
The data does not support that framing. Ownership is contracting on similar timelines in dental, medical, legal, automotive and construction, and the reporting bodies have no connection to each other. Five separate measurement systems are describing the same movement.
The ADA Health Policy Institute reports that dental practice ownership fell from 85 percent in 2005 to 73 percent. Affiliation moved in the other direction over a much shorter window. DSO affiliation doubled from 7.2 percent in 2015 to 16.1 percent of all dentists as of 2024.
The generational split is the sharper figure. ADA HPI found that 31 percent of dentists fewer than five years out of school are DSO affiliated. The population that would normally buy retiring owners out is choosing employment instead.
The AMA Physician Practice Benchmark Survey for 2024, based on 5,000 physicians with a 43 percent response rate, tracks the same slope. Physicians in wholly physician-owned practices fell to 42.2 percent from 60.1 percent in 2012. Physicians holding an ownership stake fell to 35.4 percent from 53.2 percent.
Scale moved with ownership. Physicians in practices of ten or fewer fell to 47.4 percent, below half for the first time, from 61.4 percent in 2012. Solo practice fell to 11.9 percent from 18.4 percent over the same period.
Legal consolidation now happens at the small end. Fairfax Associates reported for 2025 that 76 percent of law firm mergers involved a firm of five to twenty lawyers, up from 69 percent in each of the prior two years. The activity is no longer about large firms combining.
Automotive shows the same compression among small owners. NADA Data for 2025 puts dealership owners operating one to five stores at 90.5 percent, down from 94.4 percent in 2016. Group ownership is absorbing single-point and small-group operators.
Construction lacks a comparable published series, which is why it is usually left out of these discussions. The pattern in specialty trade contracting is nonetheless familiar to anyone working in the sector. Aging owners, no internal successor with the capital to buy, and acquirers assembling regional platforms out of mechanical, electrical and roofing firms.
What makes the grouping notable is the independence of the measurements. Dentists are counted by a dental association, physicians by a medical association, lawyers by a legal consultancy and dealers by a trade body. No shared methodology or definition connects them.
The obvious explanation is that owners are tired and buyers have capital. That is true and insufficient. Sellers are explicit about what they get in exchange, and the top answer is not relief.
The AMA found that 70.8 percent of practices that sold cited the ability to negotiate higher payment rates as a reason. Payer negotiating position is a function of size. An owner-operator cannot manufacture it internally at any level of effort.
Private equity participation is more recent than the headlines imply. The AMA reports 6.5 percent of physicians in private equity owned practices, up from roughly 4.5 percent in both 2020 and 2022. The recency shows in the acquisition dates, with 38.3 percent of private equity owned practices acquired after 2019 against 10.0 percent of hospital-owned practices.
A platform acquisition followed by add-on transactions is the standard structure. The buyer purchases one anchor firm, installs a management services organization, then acquires smaller practices that plug into the shared back office. The valuation multiple paid on the platform exceeds what add-ons receive, which is why the earnout terms differ so sharply between the two.
Nothing about dental economics resembles dealership economics. Payer mix, capital intensity, licensing and customer behavior have almost nothing in common across these five sectors. A common outcome across uncommon industries points to a cause that sits above all of them.
That cause is the collapse of the owner-operator management model. In a small professional firm, the owner is the entire management layer. The same person handles billing oversight, hiring, vendor contracts, compliance, marketing, technology decisions and scheduling, on top of practicing the profession.
The administrative content of that job has grown steadily. Payer requirements, employment regulation, cybersecurity obligations, software stacks and consumer expectations all expanded. The number of hours an owner can work did not.
Succession compounds the squeeze. When the next generation prefers employment, as the dental affiliation figures for early-career dentists show, the internal buyer disappears. An owner who cannot sell inside the firm sells outside it, and the outside buyer is a consolidator.
Look closely at what an acquirer installs after closing and the list is unremarkable. Centralized revenue cycle and billing. Payer or vendor contract negotiation handled by specialists. Standardized hiring, onboarding and compensation structures. Group purchasing. Shared marketing. Compliance and reporting run once for many locations.
None of that is clinical, legal or technical work. It is operations. The professional service delivered to the customer is frequently unchanged after an acquisition, and in many cases it is delivered by the same people in the same building.
The acquirer is monetizing the gap between what a small firm produces and what professional management would let it produce. Spreading fixed administrative cost across more locations is real scale economics. Better contract terms, better purchasing and lower cost per transaction are the returns.
Capital access is the second half of the equation and it is genuinely one-sided. Consolidators fund equipment, technology and location expansion from a balance sheet an individual owner cannot match. That advantage is real, though it applies to growth ambition rather than to daily operating performance.
That framing produces an uncomfortable question for owners who do not want to sell. If most of the value created by consolidation comes from a management layer rather than from the transaction itself, the layer is separable from the sale.
A firm that keeps its independence still has to answer the operating problem that made selling attractive. The answer is a management capability the owner does not personally supply. Full-time senior operations hires are usually unaffordable and frequently underemployed at small-firm scale.
Part-time senior leadership is the direct substitute. Owners in this position often engage a fractional COO to install the systems an acquirer would install, then step back to a lighter cadence once the operating rhythm holds. The work is sequencing, measurement and role definition rather than a permanent seat.
Structural options exist alongside the leadership question. Independent practice associations, clinically integrated networks and management services organizations formed among independents provide shared services without an equity sale. Group purchasing arrangements deliver a portion of the cost benefit that a roll-up captures.
None of these fully replicate the rate negotiation advantage that 70.8 percent of selling practices cited. Honest advice acknowledges that. Scale genuinely produces contract terms that independents cannot match, and no operating improvement closes that particular gap entirely.
What operating improvement does close is everything else. Cost per transaction, staff productivity, cash collection speed and owner time are all controllable at any size. A firm that fixes those items has narrowed the gap to the single component that requires scale.
Consolidation is not a failure state and treating it as one produces bad decisions. An owner within a few years of retirement, without an internal successor and without appetite for a multi-year operational rebuild, should probably sell. Perpetuation planning that starts too late leaves no other option worth taking.
The decision worth scrutinizing is the one made by an owner with a decade or more of working life remaining. Selling to escape administrative burden trades a permanent ownership position for temporary relief. The administrative burden was solvable. The ownership stake is not recoverable.
Owners choosing that path deserve a clear accounting of what they are exchanging. Independence has an operational price and the price is a management layer. Firms that pay it directly keep the equity.
The sequencing matters as much as the decision. A firm with documented processes, clean reporting and a functioning management structure negotiates from strength if it later chooses to sell. Building the layer improves both outcomes rather than committing the owner to only one of them.
Five industries with nothing in common are losing owner-operators at the same time, and the shared explanation is that running a small firm now requires management capacity the owner cannot personally supply. Acquirers noticed first and built a business model around it. The response available to independents is the same capability on different terms, and the firms that build it will find they were never actually choosing between selling and struggling.
What does a fractional COO actually do in a small professional firm?
The role installs the operating systems that an owner has been running informally. That typically covers revenue cycle oversight, hiring and onboarding structure, vendor and contract management, reporting cadence and clear role definitions across the team. The engagement is defined by scope and outcome rather than by hours in a chair. Most arrangements taper as internal staff take ownership of the systems that were built.
Is consolidation actually accelerating or is this normal industry cycling?
Independent sources across unrelated industries point the same direction. The ADA Health Policy Institute records dental practice ownership falling from 85 percent in 2005 to 73 percent, and the AMA records physicians in wholly physician-owned practices falling to 42.2 percent from 60.1 percent in 2012. NADA Data for 2025 shows dealership owners operating one to five stores dropping to 90.5 percent from 94.4 percent in 2016. Cyclical movement does not usually align this closely across sectors with unrelated economics.
Should my firm sell now or build management capability?
Time horizon is the deciding variable. An owner near retirement with no internal successor gains little from a multi-year operational rebuild and should evaluate offers seriously. An owner with a long runway is trading a permanent asset for relief that a management layer would also deliver. The comparison worth running is the cost of that capability against the value of the ownership stake being surrendered.
Why do practices say they sold if they were not in financial trouble?
Distress is not the leading motive in the survey data. The AMA found 70.8 percent of practices that sold cited the ability to negotiate higher payment rates as a reason. Contracting position scales with size in ways that operational excellence alone does not overcome. Owners frequently sell from a position of stability because the ceiling on independent negotiating position is structural.
Can independents get scale benefits without giving up equity?
Partially, and the qualifier matters. Independent practice associations, clinically integrated networks, group purchasing arrangements and independent-owned management services organizations deliver shared administrative cost and some purchasing advantage. These structures do not fully match the payer contracting position of a large consolidated platform. Firms should pursue them for cost and capability while being realistic about the rate ceiling.
How does this affect younger professionals entering the field?
Entry patterns have already shifted toward employment. The ADA Health Policy Institute found in 2024 that 31 percent of dentists fewer than five years out of school are DSO affiliated. That removes the traditional buyer for retiring owners and accelerates outside acquisition. Firms wanting an internal succession path need to make ownership attractive well before the owner is ready to exit.